Insurance
Excess Levels: Choosing Between Compulsory and Voluntary
The compulsory excess is set by the insurer. The voluntary amount is yours to choose, and it changes the premium immediately.
Straightforward guidance on the costs households actually face — what the options are, what they involve, and where the money quietly goes.
The compulsory excess is set by the insurer. The voluntary amount is yours to choose, and it changes the premium immediately.
One is controlled by you, the other by the recipient. That difference determines which suits a payment.
Keeping the layout turns a major project into a modest one. The savings are substantial and the constraints are manageable.
Advisories are warnings about what is deteriorating. Reading them tells you what the next year holds.
What policies actually pay for, where cover runs out, and how to avoid paying twice for the same protection.
The compulsory excess is set by the insurer. The voluntary amount is yours to choose, and it changes the premium immediately.
Standard contents policies assume a single household. Shared occupancy changes what is covered and how theft is treated.
Pays a fixed sum for defined injuries. Narrow in scope and frequently duplicated by cover you already hold.
Usually covered under other structures with a limit and security conditions that are easy to breach.
Household money decisions, examined on total cost rather than monthly payment.
One is controlled by you, the other by the recipient. That difference determines which suits a payment.
Frequency of compounding, the balance it applies to, and whether fees are included all change what a headline rate means.
Pay yourself a fixed amount from a buffer account. The buffer absorbs the variation rather than your household.
Overdraft terms, foreign usage and app quality matter more than switching incentives for most people.
Property work priced honestly, with the parts that go wrong explained before you commit.
Keeping the layout turns a major project into a modest one. The savings are substantial and the constraints are manageable.
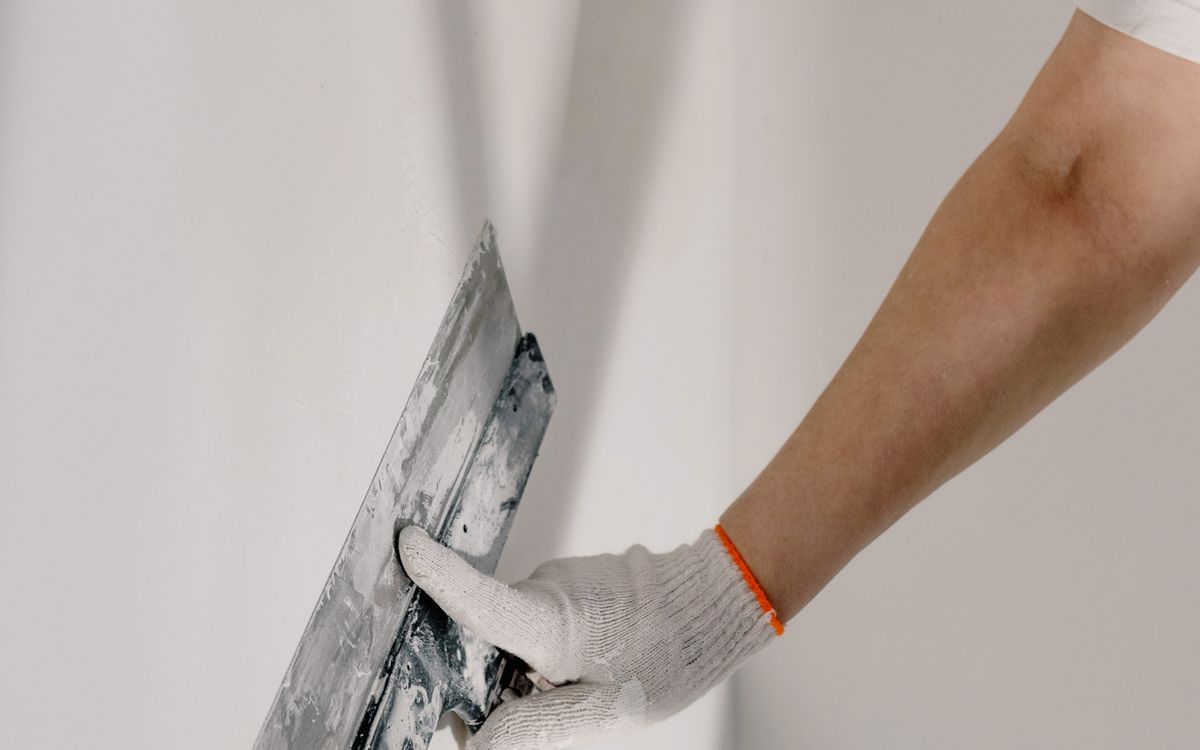
Preparation is most of the work and most of the quality difference. That determines whether doing it yourself is sensible.
An undersized radiator never heats the room. Balancing the system is free and fixes many complaints about cold rooms.
Ventilation, heating and moisture reduction address the cause. Cleaning the mould without them guarantees it returns.
Running a vehicle for less, and knowing which garage advice is worth following.
Advisories are warnings about what is deteriorating. Reading them tells you what the next year holds.
Pads are consumable and inexpensive. Leaving them too long damages discs and multiplies the bill.
Speed, tyre pressure and weight have measurable effects. Most aftermarket fuel-saving devices do not.
Independent specialists frequently offer better value than franchised dealers once a vehicle is out of warranty.
Health information set out plainly, with the evidence and the limits of it made clear.

Exemptions and prepayment arrangements exist in many systems and are claimed inconsistently.
Most shoulder pain is soft tissue related and responds to loading rather than rest.
Common, substantially underdiagnosed, and treatable. The partner usually notices before the patient does.
The examination and the eyewear are separate purchases. You are entitled to your prescription.
Technology choices for small organisations, assessed on cost, risk and what happens when it breaks.
Transaction charges matter more than the monthly fee for most businesses. Model it on your actual volumes.
Registering a company name does not give you rights in it. Trade marks and domains are separate matters.
Business tariffs offer pooled data and easier administration. The handset and airtime should be separated.

Digital records are acceptable in most systems and increasingly mandatory. The requirement is legibility and completeness.